


Report Overview
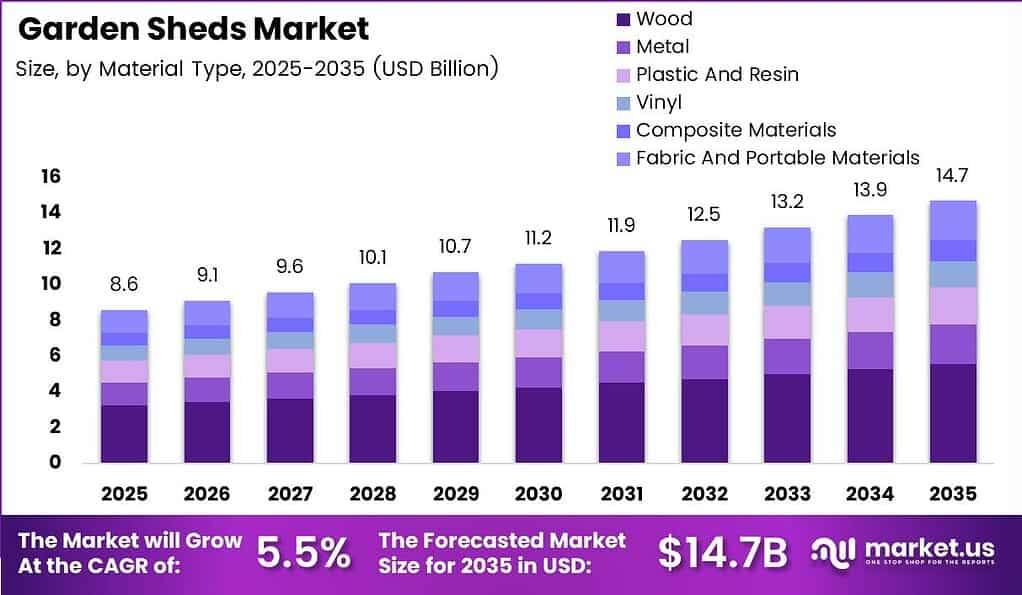
Global Garden Sheds Market size is expected to be worth around USD 14.7 Billion by 2035 from USD 8.6 Billion in 2025, growing at a CAGR of 5.5% during the forecast period 2026 to 2035.
The garden sheds market encompasses freestanding outdoor storage structures sold across residential, commercial, and industrial end users. Products span wood, metal, plastic and resin, vinyl, composite, and fabric materials. Distribution runs through offline retail, online retail, and direct sales channels. This market serves as a functional infrastructure layer for homeowners managing garden tools, bicycles, hobby equipment, and general household overflow.
Key Takeaways
- The Global Garden Sheds Market is valued at USD 8.6 Billion in 2025 and is forecast to reach USD 14.7 Billion by 2035.
- The market grows at a CAGR of 5.5% during the forecast period 2026 to 2035.
- By Material Type, Wood dominates with a 38.00% share.
- By Size, Medium sheds hold the leading position with a 46.00% share.
- By Installation Type, Prefabricated Sheds lead with a 62.00% share.
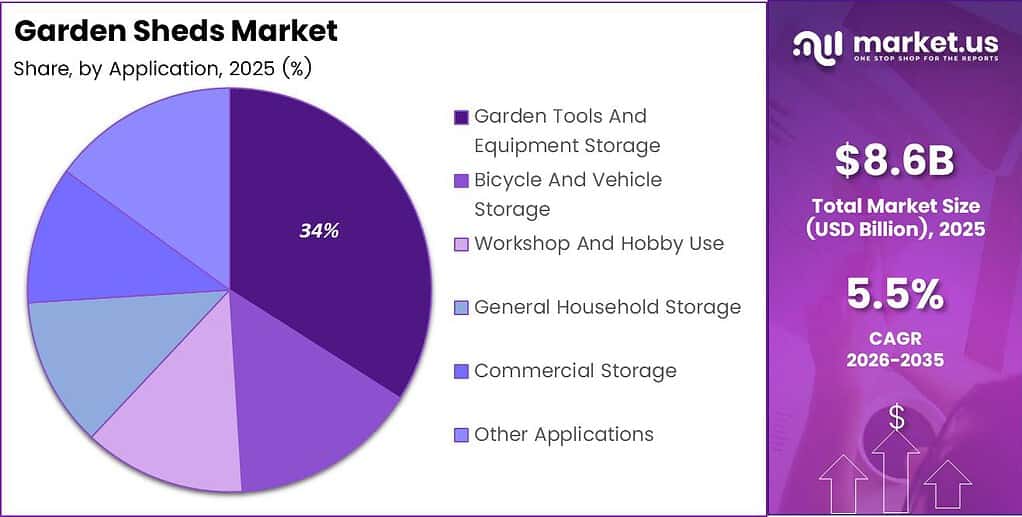
- By Application, Garden Tools and Equipment Storage dominates with a 34.00% share.
- By End User, Residential holds the dominant position with a 78.00% share.
- By Distribution Channel, Offline Retail leads with a 69.00% share.
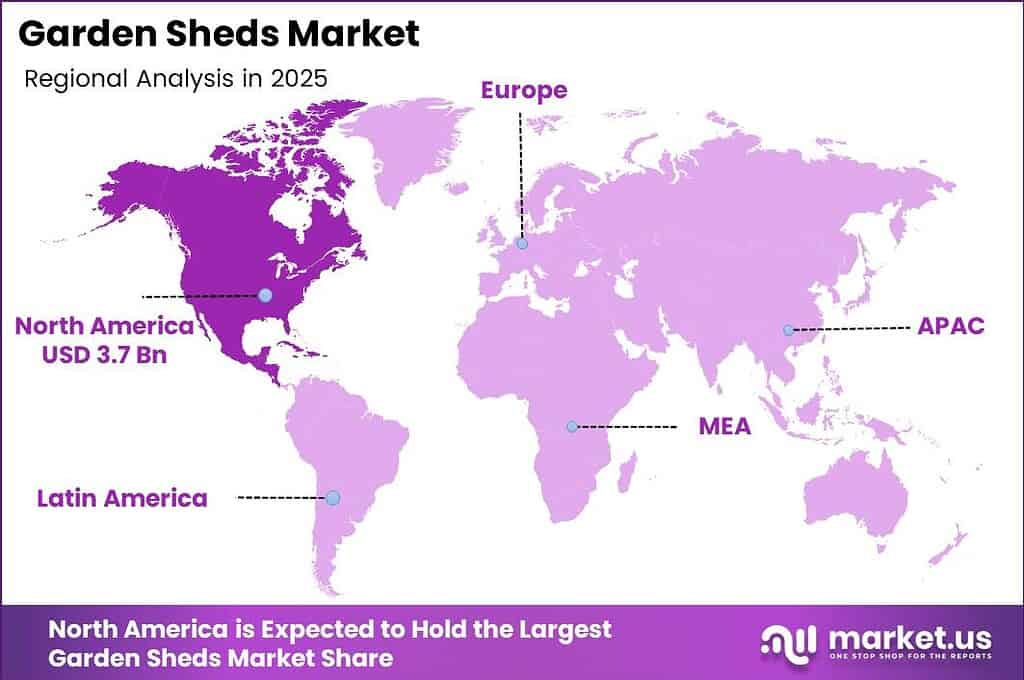
- North America dominates the regional landscape with a 44.00% market share, valued at USD 3.7 Billion.
Government investment in suburban housing infrastructure continues to shape shed demand at the foundation level. New residential construction drives first-time shed purchases as homeowners acquire garden space that requires organized storage. Housing starts and permit approvals in North America and Western Europe directly correlate with shed unit volumes, making housing policy a structural demand signal for manufacturers and distributors.
As reported by the U.S. Census Bureau, U.S. retail e-commerce sales reached $316.1 Billion in Q4 2025. This signals a structural shift in how homeowners discover and purchase outdoor storage products. Vendors with strong digital storefronts and configurable online ordering will capture an outsized share of the residential segment before offline-only competitors can respond.
Data from the Federal Reserve Economic Data shows e-commerce represented 16.7% of total U.S. retail sales in Q4 2025. This penetration level confirms online retail is no longer a secondary channel for garden sheds. In July 2025, Keter implemented an eco-conscious manufacturing shift, integrating recycled and environmentally friendly composite materials across its resin storage portfolio, a move that positions sustainable product lines to capture environmentally driven online buyers.
Material Type Analysis
Wood dominates with 38.00% due to aesthetic preference and structural versatility.
In 2025, Wood held a dominant market position in the By Material Type segment of the Garden Sheds Market, with a 38.00% share. Homeowners consistently select wood for its natural appearance, ease of customization, and compatibility with garden landscaping. This preference gives timber suppliers and wood-shed manufacturers pricing leverage in the residential premium segment, where aesthetic value drives willingness to pay above baseline storage options.
Metal sheds serve buyers who prioritize security, fire resistance, and structural longevity over aesthetic appeal. Demand for metal concentrates in bicycle and vehicle storage, commercial storage, and workshop applications where durability justifies higher upfront cost. As reported by HUD, U.S. new single-family-house sales ran at a seasonally adjusted annual rate of 745,000 units in December 2025, expanding the addressable base for both wood and metal shed purchases simultaneously.
Plastic and resin sheds address a cost-sensitive buyer segment that values low maintenance, weather resistance, and simple self-assembly. HUD data indicates the U.S. median new-house sales price reached $414,000 in December 2025. Buyers at this price point often allocate remaining budget to functional outdoor additions, making affordably priced resin sheds a logical attachment purchase alongside new homeownership.
Vinyl, composite, and fabric and portable materials together serve niche positions across the product range. Vinyl targets buyers seeking low-maintenance alternatives to wood without sacrificing aesthetics. Composite materials serve mid-range buyers bridging the gap between resin and wood. Fabric and portable formats serve renters and seasonal users who cannot install permanent structures, collectively holding the remaining market share.
Size Analysis
Medium dominates with 46.00% due to fit with standard suburban garden dimensions.
In 2025, Medium held a dominant market position in the By Size segment of the Garden Sheds Market, with a 46.00% share. Medium-sized sheds match the footprint constraints of typical suburban lots while offering enough interior volume to store lawnmowers, garden tools, bicycles, and seasonal equipment. This functional fit makes medium sheds the default purchase across the residential segment, anchoring revenue for mainstream manufacturers and big-box retail distributors.
Small sheds serve urban and semi-urban buyers with limited garden space, renters requiring portable or non-permanent solutions, and homeowners adding secondary storage alongside an existing shed. Demand in this tier is structurally supported by high-density housing growth in European and Asia-Pacific markets where garden footprints constrain larger installations. Small sheds carry lower average selling prices but benefit from faster repurchase cycles and higher online conversion rates.
Large sheds occupy the premium end of the size spectrum and serve buyers converting outdoor space into workshops, hobby rooms, or multi-function utility areas. This segment commands the highest unit revenue and the widest margin on accessories and add-ons such as shelving, insulation, ventilation, and electrical routing. However, large sheds face the greatest exposure to permit and zoning restrictions, limiting their addressable market to suburban and rural properties with sufficient setback space.
Installation Type Analysis
Prefabricated Sheds dominate with 62.00% due to cost efficiency and faster installation timelines.
In 2025, Prefabricated Sheds held a dominant market position in the By Installation Type segment of the Garden Sheds Market, with a 62.00% share. Prefabricated sheds reduce buyer risk by delivering pre-engineered components that minimize on-site labor, shorten installation windows, and lower total purchase cost versus custom alternatives. This structure makes prefabricated sheds the default choice across mass-market retail and online channels, where buyers value speed of delivery and ease of assembly over bespoke design.
Custom-built sheds serve homeowners and commercial buyers who require non-standard dimensions, specialized materials, or site-specific configurations that prefabricated formats cannot accommodate. This segment commands the highest unit price and the widest customization margin, but faces the longest lead times and the highest dependency on skilled installation labor. Custom builds remain concentrated in the premium residential and commercial sub-segments, where buyers accept extended timelines in exchange for precision fit and aesthetic control.
Modular sheds occupy a structural middle ground between prefabricated and custom formats by offering expandable, reconfigurable designs that allow buyers to add sections as storage needs evolve. This flexibility appeals to homeowners who anticipate future space requirements without committing to full custom-build costs at the point of initial purchase. Modular formats also benefit from repeat hardware and component sales as buyers expand existing installations rather than replacing entire structures.
Application Analysis
Garden Tools and Equipment Storage dominates with 34.00% due to universal ownership of lawn and garden equipment.
In 2025, Garden Tools and Equipment Storage held a dominant market position in the By Application segment of the Garden Sheds Market, with a 34.00% share. The near-universal ownership of lawnmowers, trimmers, garden tools, and irrigation equipment among suburban homeowners creates a baseline storage need that no alternative product category fulfills as cost-effectively as a garden shed. This positions garden tool storage as the primary demand anchor and acquisition driver for first-time shed buyers.
Bicycle and vehicle storage addresses a high-value application that supports above-average unit size and premium pricing. Buyers selecting sheds for this purpose prioritize security features, floor load capacity, and access width over aesthetic appearance. This application cluster supports double-door configurations, reinforced flooring, and anchor-compatible base systems, all of which carry higher margin than standard tool-storage configurations.
Workshop and hobby use drives purchase decisions among buyers who intend to occupy the shed actively rather than use it purely for passive storage. This application requires electrical-ready configurations, insulation, windows for natural light, and bench-compatible internal dimensions. General household storage, commercial storage, and other applications together serve overflow and utility needs across residential and commercial buyer types, collectively holding the remaining share of the application segment.
End User Analysis
Residential dominates with 78.00% due to suburban homeownership driving primary shed demand.
In 2025, Residential held a dominant market position in the By End User segment of the Garden Sheds Market, with a 78.00% share. Suburban homeowners form the structural base of garden shed demand because they combine the garden space, the tool and equipment inventory, and the discretionary home improvement budget necessary to justify a shed purchase. This concentration means residential buyer sentiment, housing activity, and home improvement confidence function as the primary demand levers for the entire market.
Commercial end users purchase sheds for site storage, groundskeeping equipment containment, and utility infrastructure across hospitality, education, landscaping, and facilities management operations. Commercial buyers tend toward metal and modular formats for durability, standardization, and replaceability across multi-site operations. This sub-segment offers manufacturers a path to bulk-order revenue with less price sensitivity than the retail residential channel.
Distribution Channel Analysis
Offline Retail dominates with 69.00% due to buyer preference for physical inspection before purchase.
In 2025, Offline Retail held a dominant market position in the By Distribution Channel segment of the Garden Sheds Market, with a 69.00% share. Garden sheds are high-involvement purchases where buyers assess physical dimensions, material quality, and structural integrity before committing. This evaluation behavior keeps big-box home improvement retailers, specialist garden centers, and shed dealer networks as the primary conversion points for the market. Offline channels also support upselling of installation services, foundation kits, and accessory packages at the point of sale.
Online retail captures a growing share of shed transactions by serving buyers who have already decided on a format and seek price comparison, delivery convenience, and broader product range than local stores can stock. Direct sales channels serve custom-build buyers, commercial accounts, and buyers in geographies underserved by retail networks. Both channels carry higher return rates and greater last-mile freight complexity than offline retail, which constrains gross margin for vendors without purpose-built logistics infrastructure.
Key Market Segments
By Material Type
- Wood
- Metal
- Plastic And Resin
- Vinyl
- Composite Materials
- Fabric And Portable Materials
By Size
- Small
- Medium
- Large
By Installation Type
- Prefabricated Sheds
- Custom-Built Sheds
- Modular Sheds
By Application
- Garden Tools And Equipment Storage
- Bicycle And Vehicle Storage
- Workshop And Hobby Use
- General Household Storage
- Commercial Storage
- Other Applications
By End User
- Residential
- Commercial
- Industrial
By Distribution Channel
- Offline Retail
- Online Retail
- Direct Sales
Regional Analysis
North America Dominates the Garden Sheds Market with a Market Share of 44.00%, Valued at USD 3.7 Billion
North America commands 44.00% of the global garden sheds market, generating USD 3.7 Billion in 2025. High suburban homeownership rates, large residential lot sizes, and a deeply embedded home improvement culture create structural demand that no other region matches at scale. The United States anchors this position, with big-box retail networks providing manufacturers with high-volume distribution infrastructure across all major metro and suburban markets. In February 2026, ShelterLogic Group expanded its structural protection portfolio with its American-made STEELPEAK Carport Series alongside an expanded Essential Steel Shed line, reinforcing North America’s position as the primary product launch market.
Asia Pacific represents the fastest-growing regional opportunity as rising middle-class homeownership, suburban expansion, and growing garden culture in markets such as Australia, China, and India drive first-time shed adoption. Suburban household formation in selected Asia-Pacific markets adds a net new buyer base that North America and Europe cannot replicate, given their more mature installation rates. This demographic shift signals a multi-year demand runway for entry-level and mid-range prefabricated shed formats targeting new suburban homeowners.
Europe contributes a mature but structurally important share of global garden shed demand, driven by the United Kingdom, Germany, and France where garden culture is deeply integrated into residential lifestyle. Latin America and the Middle East and Africa regions hold smaller collective shares but offer long-term optionality for manufacturers seeking geographic diversification beyond saturated North American and European markets.
Key Regions and Countries
North America
- US
- Canada
Europe
- Germany
- France
- The UK
- Spain
- Italy
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of APAC
Latin America
- Brazil
- Mexico
- Rest of Latin America
Middle East and Africa
- GCC
- South Africa
- Rest of MEA
Drivers
Outdoor living upgrades have repositioned garden sheds from low-priority storage purchases into functional extensions of the residential home. As per our research, 33% of homeowners upgrading outdoor areas in 2024 reported extending living space as a key objective. This behavioral shift allows manufacturers to bundle sheds with decking, fencing, and lighting projects, lifting average order value and reducing price-only competition across retail channels.
Home improvement recovery across North America and Western Europe restores cross-selling volume through specialist dealers and big-box retail. DIY kit adoption adds a short-term conversion pathway in markets where assembly-ready formats reduce buyer hesitation. Suburban household formation in the United States, Canada, and Australia sustains a net new buyer base, while gardening equipment storage and weather-resistant material demand extend the purchase rationale beyond seasonal and discretionary cycles into year-round functional need.
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Outdoor Living Upgrades | +1.2% | North America, Western Europe, Australia | Short term (≤ 2 years) |
| Home Improvement Recovery | +0.9% | North America, United Kingdom, Western Europe | Short term (≤ 2 years) |
| Gardening Equipment Storage | +0.7% | North America, Europe, Japan | Medium term (2–4 years) |
| Suburban Household Formation | +0.6% | United States, Canada, Australia, selected Asia-Pacific markets | Medium term (2–4 years) |
| DIY Kit Adoption | +0.5% | North America, United Kingdom, Germany, France | Short term (≤ 2 years) |
| Weather-Resistant Material Demand | +0.4% | Coastal, high-rainfall, and temperature-extreme markets | Medium term (2–4 years) |
Restraints
Permit and zoning limits represent the most direct structural brake on shed sales in developed markets. In England and Wales, outbuildings within 2 metres of a boundary face a 2.5-metre height restriction and cannot exceed 50% of domestic curtilage under permitted-development rules. In the United States, permits are often required beyond approximately 120 square feet or when utilities or permanent foundations are involved. These thresholds suppress premium and large-format products by adding buyer uncertainty and approval cost before a purchase completes.
High consumer financing costs reduce discretionary outdoor spending across North America, the United Kingdom, and Europe, compressing the buyer pool for mid-range and premium shed configurations. Timber and steel cost exposure elevates input costs globally for import-dependent manufacturers. Homeowner association restrictions in the United States, Canada, and Australia disqualify entire property segments from shed installation. Seasonal purchase deferrals in cold-weather markets further concentrate revenue into short selling windows, limiting manufacturer revenue predictability across the annual cycle.
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Permit and Zoning Limits | -1.1% | North America, United Kingdom, Europe, dense urban markets | Short term (≤ 2 years) |
| Small Garden Footprints | -0.8% | Urban Europe, Japan, South Korea, high-density Asia-Pacific | Medium term (2–4 years) |
| High Consumer Financing Costs | -0.7% | North America, United Kingdom, Europe | Short term (≤ 2 years) |
| Timber and Steel Cost Exposure | -0.6% | Global, especially import-dependent markets | Short term (≤ 2 years) |
| Homeowner Association Restrictions | -0.4% | United States, Canada, Australia | Medium term (2–4 years) |
| Seasonal Purchase Deferrals | -0.3% | Cold-weather and high-rainfall markets | Short term (≤ 2 years) |
Challenges
Installer labor scarcity limits the serviceable sales ceiling for higher-value shed configurations that require assembly, anchoring, and electrical-ready finishing. Industry estimates indicate a need for approximately 723,000 construction-worker hires annually, while 65% of surveyed builders reported shortages of finish carpenters in 2024. This labor constraint pushes installation subcontractor costs upward and extends booking windows, reducing dealer conversion rates on premium products that require on-site professional completion.
Last-mile freight complexity adds cost and delay to shed deliveries across rural and peri-urban markets in North America and Europe. Multi-material supply volatility exposes manufacturers to simultaneous input cost pressure across timber, steel, and resin. Assembly failure risk in DIY channels drives return rates that erode e-commerce and big-box retail margins. Climate durability demands in coastal, wildfire-prone, and snow-load markets require material upgrades that increase production cost without proportional lift in consumer willingness to pay.
| Challenge | (~) % CAGR Friction Drag | Geographic Relevance | Mitigation Horizon |
|---|---|---|---|
| Installer Labor Scarcity | -0.9% | North America, United Kingdom, Australia, Western Europe | Medium term (2–4 years) |
| Last-Mile Freight Complexity | -0.7% | North America, Europe, rural and peri-urban markets | Short term (≤ 2 years) |
| Multi-Material Supply Volatility | -0.6% | Global | Medium term (2–4 years) |
| Assembly Failure Risk | -0.5% | Global DIY channels | Short term (≤ 2 years) |
| Climate Durability Demands | -0.5% | Coastal, wildfire-prone, snow-load, and tropical markets | Long term (≥ 4 years) |
| Returns and Damage Costs | -0.4% | Global e-commerce and big-box retail channels | Short term (≤ 2 years) |
Opportunities
Shed-to-workspace conversion opens a premium segment that most manufacturers have not yet addressed at scale. As per our research, 33% of outdoor renovators in 2024 sought to extend usable living areas, validating latent demand for configurable studio, hobby-room, and home-office shed formats. Suppliers that build insulated, glazed, and electrically compatible products alongside managed installation bundles can expand gross margin by roughly 5 to 10% versus standard storage configurations.
Installation-as-a-service bundles address the labor scarcity challenge while creating a recurring customer relationship that extends beyond the initial product sale. Direct digital configuration tools allow buyers to design, price, and order sheds online without visiting a physical retailer, opening geographic reach in underserved markets. Recycled resin premiumization targets environmentally motivated buyers in Europe, North America, and Japan, while micro-shed urban formats address high-density cities in Europe and Asia-Pacific where standard shed footprints exceed available garden space.
| Opportunity | (~) % Potential CAGR Upside | Geographic Relevance | Execution Window |
|---|---|---|---|
| Shed-to-Workspace Conversion | +1.3% | North America, United Kingdom, Western Europe, Australia | Medium term (2–4 years) |
| Installation-as-a-Service Bundles | +1.0% | North America, Europe, Australia | Short term (≤ 2 years) |
| Direct Digital Configuration | +0.8% | Global, led by mature e-commerce markets | Short term (≤ 2 years) |
| Recycled Resin Premiumization | +0.7% | Europe, North America, Japan | Medium term (2–4 years) |
| Micro-Shed Urban Formats | +0.6% | Europe, Japan, South Korea, dense Asia-Pacific cities | Medium term (2–4 years) |
| Dealer Network Consolidation | +0.5% | Fragmented regional markets globally | Long term (≥ 4 years) |
Key Company Insights
Keter Group holds a structural advantage in the global resin shed segment through its vertically integrated manufacturing and broad retail distribution across North America and Europe. Following a September 2025 share allotment that brought total capital to €705,141.80, the group signaled continued investment appetite. In July 2025, Keter’s integration of recycled composite materials across its core resin lines positions it ahead of the recycled resin premiumization opportunity identified across European and North American markets.
Lifetime Products, Inc. competes through high-volume, competitively priced resin and metal shed formats distributed through mass-market retail. In January 2025, Biohort introduced the Romeo patio locker with a distinctive X-design aesthetic alongside expanded customizable, heat-insulated Pergola collections, signaling that European premium players are broadening product scope to capture the workspace and outdoor lifestyle segment before mainstream manufacturers respond. As per our research, global trade reached $33 Trillion in 2024, reflecting supply chain conditions that affect raw material procurement costs for all manufacturers in this market.
Key Players
- Keter Group
- Lifetime Products, Inc.
- Suncast Corporation
- ShelterLogic Group
- Arrow Storage Products
- Rubbermaid
- Tuff Shed, Inc.
- Canopia by Palram
- Biohort GmbH
- Forest Garden Ltd.
- Mercia Garden Products
- YardMaster International
- Absco Sheds
- Cedarshed Industries
- DuraMax Building Products
Recent Developments
- April 2026 – ShelterLogic Group launched its premium Shirudo Series, introducing a large-capacity metal garden shed series engineered from precision-crafted steel to provide heavy-duty security and enhance property equity.
- March 2026 – Arrow Storage Products, a ShelterLogic Group brand, was ranked #1 for Best Outdoor Storage in the Newsweek Readers’ Choice Awards, validating consumer trust during its milestone 80th anniversary year of steel shed manufacturing.
Report Scope
| Report Features | Description |
|---|---|
| Market Value (2025) | USD 8.6 Billion |
| Forecast Revenue (2035) | USD 14.7 Billion |
| CAGR (2026-2035) | 5.5% |
| Base Year for Estimation | 2025 |
| Historic Period | 2020-2024 |
| Forecast Period | 2026-2035 |
| Report Coverage | Revenue Forecast, Market Dynamics, Market Opportunity Analysis, Technology and Innovation Landscape, Competitive Landscape, Recent Developments |
| Segments Covered | By Material Type (Wood, Metal, Plastic And Resin, Vinyl, Composite Materials, Fabric And Portable Materials), By Size (Small, Medium, Large), By Installation Type (Prefabricated Sheds, Custom-Built Sheds, Modular Sheds), By Application (Garden Tools And Equipment Storage, Bicycle And Vehicle Storage, Workshop And Hobby Use, General Household Storage, Commercial Storage, Other Applications), By End User (Residential, Commercial, Industrial), By Distribution Channel (Offline Retail, Online Retail, Direct Sales) |
| Regional Analysis | North America (US and Canada), Europe (Germany, France, The UK, Spain, Italy, and Rest of Europe), Asia Pacific (China, Japan, South Korea, India, Australia, and Rest of APAC), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa (GCC, South Africa, and Rest of MEA) |
| Competitive Landscape | Keter Group, Lifetime Products, Inc., Suncast Corporation, ShelterLogic Group, Arrow Storage Products, Rubbermaid, Tuff Shed, Inc., Canopia by Palram, Biohort GmbH, Forest Garden Ltd., Mercia Garden Products, YardMaster International, Absco Sheds, Cedarshed Industries, DuraMax Building Products |
| Customization Scope | Customization for segments, region/country-level will be provided. Additional customization can be done based on requirements. |
| Purchase Options | We have three licenses to opt for: Single User License, Multi-User License (Up to 5 Users), Corporate Use License (Unlimited User and Printable PDF) |








